The Money Story Your Devices Are Already Telling
Most people still think of money as a stack of separate decisions. One grocery trip here, one streaming charge there, one late night online order that felt smart until the next morning. But your financial life does not actually exist as scattered moments anymore. It exists as data. Your bank app sees patterns. Your credit card statement sees habits. Your inbox sees renewal dates. Your calendar sees due dates. Even your rideshare receipts and food delivery history can sketch a picture of what your month really looks like.
That can feel a little unsettling at first. It can also be useful. If your financial life already leaves a trail, the real question is whether you are the one using that trail on purpose. Plenty of people reach out for help through tools like credit counseling when bills start to feel unmanageable, but there is also value in learning how to read the signals your own digital footprint is sending before things spiral. The goal is not to become obsessed with every transaction. It is to turn the information you already have into something clearer, calmer, and more practical.
The old budgeting mindset often assumed that you had to build awareness from scratch. Save every receipt. Type every expense into a spreadsheet. Try to remember what happened three Tuesdays ago. That system worked for some people, but for many it failed because it depended on perfect memory and endless discipline. Now, most of the raw material is already collected for you. The challenge has shifted. It is no longer, “How do I track everything?” It is, “How do I make sense of what is already being tracked?”
Your Financial Habits Are More Visible Than You Think
Think about what your digital trail contains. It shows how often you eat out at the end of a stressful week. It shows whether subscription charges pile up quietly. It shows whether small convenience purchases are replacing bigger planned purchases. It can reveal if you tend to overspend right after payday, or if you get hit with multiple automatic charges during the same five day window each month.
That kind of visibility matters because many money problems do not begin with one dramatic mistake. They begin with repeated friction. A forgotten free trial. A payment date that lands before your paycheck clears. A tendency to solve time problems with spending. Data is good at catching repetition, and repetition is where habits live.
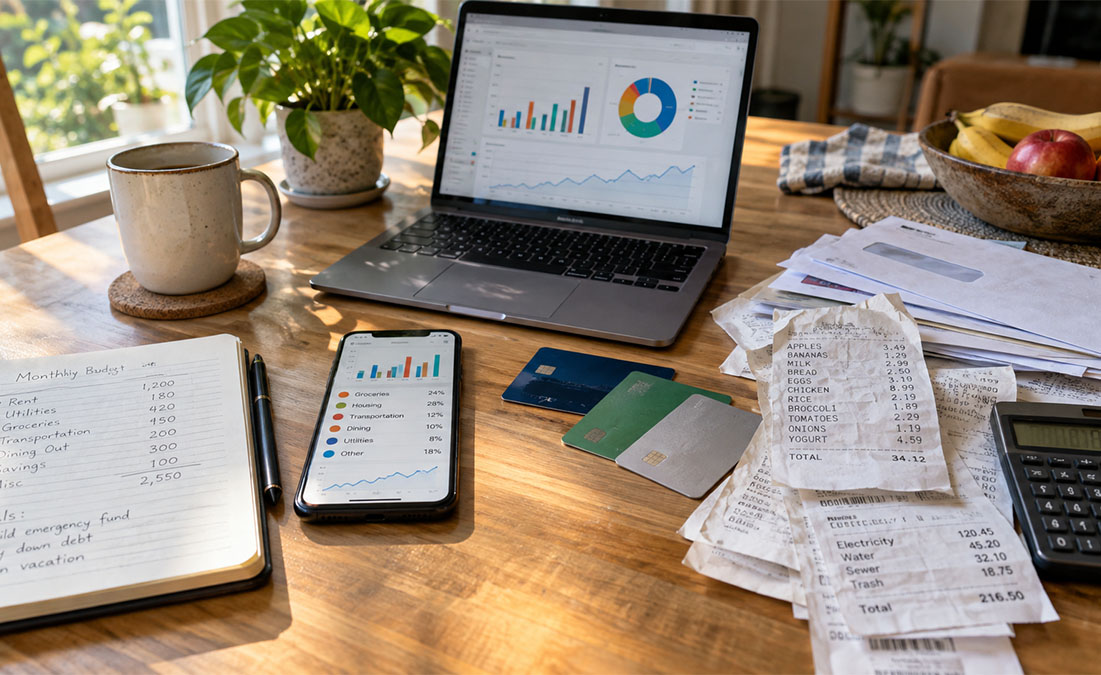
This is one place where AI can actually be helpful, if you use it carefully. A secure AI tool can sort transaction categories, summarize spending trends, identify duplicate subscriptions, and highlight unusual changes much faster than most people can do manually. Instead of staring at three months of statements and feeling your eyes glaze over, you can ask for a plain language summary of where your money seems to be going.
The Best Use of AI Is Interpretation, Not Confession
A lot of people approach financial tools emotionally. They want reassurance, motivation, maybe even absolution. That is understandable, but it is not the strongest role for AI. The better role is interpretation. Let the system help you organize, compare, and summarize. Let it point out that utility costs rose, restaurant spending doubled, or debt payments are consuming more of your income than you realized.
What you should not do is treat a free public chatbot like a private vault for highly sensitive details. Full account numbers, Social Security numbers, passwords, tax documents, and other identifying information do not belong in casual prompts. Convenience can make people careless, especially when a tool sounds friendly and responsive.
A smarter approach is to sanitize the data first. Remove names, account numbers, addresses, and anything that could expose you if the information were mishandled. Then use the cleaned data for pattern finding. If you want an outside benchmark for protecting yourself online, the Federal Trade Commission explains common warning signs of identity theft and what to watch for in your statements and accounts through its guide to what to know about identity theft. That matters because the same digital trail that helps you understand your habits can also reveal when something is off.
Your Transactions Often Reflect Your Schedule More Than Your Values
One of the most interesting things financial data can show is that spending is not always about desire. Often, it is about timing. People spend because they are rushed, tired, distracted, or trying to solve a short term problem fast. The extra delivery fees, convenience store runs, and duplicate purchases are not always signs of bad priorities. Sometimes they are signs of a life with too much friction.
That is a useful shift in perspective. If your data shows repeated spending spikes on certain days, the answer may not be “I need more self control.” It may be “I need a better system for those hours.” Maybe Tuesday is the day you work late and order takeout. Maybe the first weekend of the month is when every family errand turns into impulse spending. Data can reveal pressure points. Once you see them, you can design around them.
This is where AI becomes less like a lecture and more like a mirror. It can help connect spending to timing, categories, and sequences. Maybe every overdraft risk follows a cluster of auto payments. Maybe every unusually expensive week starts with one missed planning task. Patterns like these are hard to catch in real time, but easy to spot in hindsight when your information is organized.
Security Has To Be Part of the Plan
If you are going to use digital tools to understand your money, security cannot be an afterthought. The more connected your accounts are, the more important basic protection becomes. Strong passwords, multifactor authentication, software updates, and skepticism toward suspicious messages are not tech extras. They are part of financial self defense.
That is especially true because scams increasingly aim at the same accounts that hold your money data. A fake bank alert, a spoofed payment issue, or a phishing email about a subscription renewal can trick people into handing over exactly the information they are trying to manage. The Cybersecurity and Infrastructure Security Agency offers simple guidance on recognizing and reporting phishing, which is worth treating as part of any modern money routine.
In other words, financial organization and digital safety now belong in the same conversation. If your budget lives on your phone and your statements live in your email, protecting your devices is part of protecting your cash flow.
A Useful Summary Beats a Perfect Spreadsheet
There is a quiet trap in personal finance content. It often makes people feel like they need a flawless system before they can make better decisions. But most people do not need a perfect spreadsheet. They need a useful summary. They need to know which expenses are fixed, which are flexible, which are rising, and which are draining money without adding much value.
That is why a data first mindset can be so refreshing. Instead of asking yourself to remember everything, you start with the evidence.
- What repeated charges are showing up?
- What categories expanded over the past ninety days?
- Which expenses feel necessary, and which ones are really stress responses in disguise?
Good analysis does not judge you. It simply gives you a more honest map.
The Point Is Awareness You Can Act On
Your financial life already has data. That is true whether you use it or not. Every statement, alert, receipt, and renewal email is part of a larger story about how money moves through your life. The real opportunity now is not just tracking. It is translation.
When you use secure tools wisely, your data can stop being a pile of digital clutter and start becoming feedback. It can show you where your routines help, where they hurt, and where one small change could matter more than a dramatic overhaul. That is a much more realistic way to improve your finances. Not by pretending you are starting from zero, but by realizing the clues have been there all along.