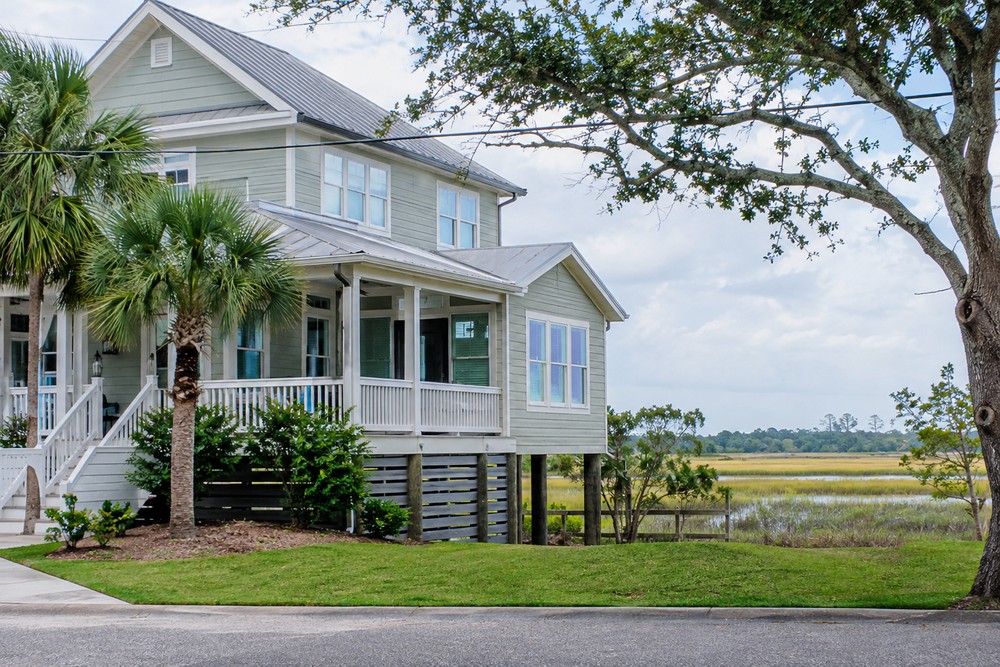
In Pawleys Island, the listing price is only the starting point. A home near the ocean, creek, marsh, golf course, or Intracoastal Waterway can bring a distinctive Lowcountry lifestyle, but it can also come with ownership costs that deserve close attention before an offer is made.
Buyers who want neighborhood-level guidance can work with Pawleys Island SC real estate agents Taylor Keenan Team. The Taylor Keenan Team provides real estate services for buyers, sellers, and investors throughout Pawleys Island, Murrells Inlet, Georgetown, Garden City, and the coastal South Strand, making local insight especially valuable when comparing insurance, property condition, community rules, and long-term ownership considerations.
Build a Complete Monthly Housing Budget
A mortgage payment alone does not show the true cost of a coastal property. Before narrowing a search, create a monthly budget that includes principal and interest, property taxes, homeowners insurance, flood insurance, wind or named-storm coverage when applicable, HOA or condo fees, utilities, internet, and a reserve for maintenance.
For a second home or rental property, add lawn care, cleaning, vacant-home checks, furnishing, management fees, and travel costs. A lower-priced condo may look like the better deal until its association fees, master policy costs, elevator maintenance, or pending assessment are factored in. By contrast, a more expensive single-family home may have no HOA fee but require the owner to budget independently for its roof, landscaping, exterior upkeep, and drainage.
Check Flood Risk Before Making an Offer
Flood risk is not limited to homes directly on the beach. Heavy rain, tidal conditions, drainage limitations, low-lying roads, nearby creeks, and marsh-adjacent locations can all affect access and water exposure. Review the current flood map, but do not let the map be the only source of information. Ask about prior flooding, water intrusion, repaired drywall or flooring, drainage improvements, and whether nearby streets become difficult to use during major rain events.
A lender generally requires flood insurance when a mortgaged property is located in a Special Flood Hazard Area. Flood coverage is usually separate from a standard homeowners policy. The questions buyers should ask about flood and disaster risk can help structure conversations with the seller, inspector, insurer, and lender before due diligence ends.
Get Insurance Quotes Early
Do not wait until the final days before closing to investigate insurance. Request quotes as soon as the property is under consideration, particularly for homes near the coast or in communities with shared structures. Ask each insurer about deductibles, exclusions, coverage limits, roof-age requirements, wind coverage, and the availability of replacement-cost coverage.
Also clarify whether the policy addresses detached buildings, screened porches, decks, docks, exterior HVAC equipment, personal property, and temporary housing after a covered loss. If the home may become a rental, confirm that the policy fits the intended use rather than assuming a standard owner-occupied policy will apply.
Read HOA and Condo Documents Carefully
Association documents can reveal costs that are not obvious during a showing. Review the monthly fee, what it covers, the latest budget, reserve balance, meeting minutes, insurance information, and any planned capital projects. For condominiums, ask how the association handles roofs, elevators, pools, siding, stairways, parking areas, drainage, and shared structures.
A low monthly fee is not automatically a bargain. It may mean the community has limited reserves for aging components or is postponing work that could later require a special assessment. Buyers considering short-term rentals should also verify in writing the rental rules, minimum lease periods, registration requirements, parking limits, pet rules, and occupancy restrictions.
Inspect for Coastal Wear and Deferred Maintenance
Salt air, humidity, wind-driven rain, and intense sun can be hard on building materials. A general home inspection is important, but some properties warrant added expertise. Pay close attention to roof age and fastening, window and door seals, water staining, corrosion on railings and mechanical components, deck framing, stairs, crawl spaces, ventilation, mold, wood rot, and termite evidence.
Evaluate drainage, grading, vapor barriers, sump pumps, and the condition of elevated foundations where applicable. If the property includes a seawall, bulkhead, dock, or shared waterfront access, determine who owns it, who maintains it, and whether recent repairs or inspections are available. A structural engineer, roofer, pest professional, or marine contractor may be appropriate when the general inspection identifies a concern.
Look Beyond the View
A view of dunes, water, live oaks, or a fairway can be meaningful, but daily practicality matters too. Drive the route to grocery stores, medical services, schools, beaches, and major roads. Check parking, seasonal traffic, nearby construction, public access points, and the route you would use during severe weather or heavy rain.
For Pawleys Island buyers, it is also worth comparing homes on the island with properties farther inland in the South Strand. The right choice may be the home that balances lifestyle, access, maintenance demands, and insurance comfort rather than the one with the most dramatic view.
Match the Property to Its Intended Use
Primary Residence
Prioritize everyday convenience, reliable internet, storage, storm preparation, and resale appeal. A home that works well in July should also fit your routine during quieter months.
Vacation Home or Investment Property
Budget for periods when the home is vacant. Confirm who will inspect the property, respond to leaks, coordinate repairs, prepare it for storms, and manage cleaning or guest turnover. For rentals, use conservative income assumptions and make sure association rules allow the rental plan.
Ask Better Questions During Due Diligence
- Has the property ever flooded, leaked, or sustained storm damage?
- What insurance claims, nonrenewals, or coverage challenges have occurred?
- What are the current annual costs for homeowners, flood, wind, utilities, and HOA fees?
- Are special assessments, major repairs, or reserve-funded projects pending?
- What improvements were completed after prior storms or water events?
- Who maintains drainage systems, roads, seawalls, docks, and shared amenities?
- What restrictions apply to rentals, pets, renovations, vehicles, and parking?
Use a Buy-or-Wait Test
Before removing contingencies, ask whether the home still fits if insurance costs increase, rental income is lower than hoped, or one major repair is needed during the first year. Compare the total annual cost of ownership with nearby alternatives, not just the list price or lender estimate.
Coastal ownership can be rewarding when the financial picture is clear. A careful review of insurance, flood exposure, association documents, inspections, access, and repair needs gives Pawleys Island buyers a stronger basis for choosing a home that supports both their lifestyle and their budget.